

Are you looking for a Chapter 7 bankruptcy lawyer in Bolingbrook, IL?
At Madden Law LLC, we are trusted Chapter 7 bankruptcy counsel for individuals and business owners throughout Bolingbrook.
If credit cards, medical bills, or personal loans have grown beyond what you can repay, Chapter 7 bankruptcy can eliminate those debts, usually within a few months. In Chapter 7, a court-appointed trustee reviews your property, and the court enters a discharge, an order ending your legal obligation to pay most unsecured debts. Our Bolingbrook, IL Chapter 7 bankruptcy attorney can show you what you would keep before you file.
Madden Law LLC represents individuals and small businesses in Chapter 7 cases, drawing on more than 20 years of legal experience. Book a free consultation today.
Chapter 7 Bankruptcy Lawyer Bolingbrook, IL
A Chapter 7 bankruptcy lawyer helps people who cannot realistically repay their unsecured debts, such as credit card balances and medical bills, eliminate them through the federal bankruptcy court. The lawyer confirms that you qualify, prepares the forms that list your income, debts, and property, and claims the exemptions that protect what you own. If the trustee or a creditor raises a question, the lawyer responds on your behalf.
About 9.2% of Bolingbrook residents live below the poverty line, according to Census Bureau poverty data. Households with lower incomes often qualify for Chapter 7 without difficulty, because the full means test applies only when income is above the Illinois median. For other Bolingbrook households, a Chapter 7 attorney in Bolingbrook, IL can run the numbers before filing.
Types of Chapter 7 Bankruptcy Cases We Handle in Bolingbrook
Chapter 7 is designed for debts that you do not need to keep paying in order to keep your property. As Chapter 7 bankruptcy attorneys serving Bolingbrook, we most often help clients with the following.
- Credit card debt. Credit card balances are unsecured, which means no property backs the debt. They are usually eliminated in full, and collection calls on those accounts must stop once you file.
- Medical bills. Hospital, surgery, and emergency room bills are treated the same as other unsecured debt. Collection agencies that have bought medical accounts are bound by the discharge as well.
- Personal loans and payday loans. Signature loans, online installment loans, and payday loans are generally dischargeable. We review recent borrowing closely, because large purchases or cash advances shortly before filing can draw objections.
- Garnishments and collection lawsuits. A bankruptcy filing usually halts a paycheck garnishment and any pending collection suit. A judgment that a creditor has already won is usually based on a debt that Chapter 7 can eliminate.
- Deficiency balances after repossession. When a lender repossesses and sells a car for less than you owe, the remaining balance is typically an unsecured debt that Chapter 7 can discharge.
- A home you cannot afford to keep. If the mortgage is no longer sustainable, Chapter 7 can end your personal liability on the loan. The lender may still foreclose, but it generally cannot pursue you for the shortfall afterward.
- Small business closures. When a business has stopped operating, Chapter 7 gives the business an orderly way to close through a trustee. For sole proprietors, business and personal debts are handled in the same case. We also review any personal guarantees the owner signed, because those debts can follow the owner after the business closes.
Why Choose Madden Law LLC as my Chapter 7 Bankruptcy Lawyer in Bolingbrook, IL?
Knowing What You Keep Before You File
The most common fear about Chapter 7 is losing a house, car, or retirement account. Before you file, we list everything you own and match each item to an Illinois exemption, so you know in advance what you will keep. As a bankruptcy lawyer in Bolingbrook, IL, we also tell you plainly if any property would be at risk. Most individual Chapter 7 filers keep everything they own, and the trustee sells nothing.
Two Decades of Practice and a Treatise Chapter on the Means Test
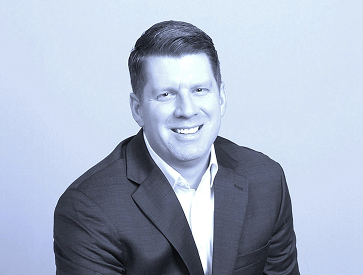
David Madden spent more than two decades representing corporations and high-net-worth individuals at large national and regional firms before founding Madden Law LLC in 2025. He is a former infantry Corporal in the Marine Corps Reserve and a member of the National Association of Consumer Bankruptcy Attorneys (NACBA). For the 2025 edition of the Illinois Institute for Continuing Legal Education's consumer bankruptcy guide, he wrote the means test chapter and the grounds for dismissing or converting a Chapter 7 case.
Understanding Chapter 7 Bankruptcy Cases
Chapter 7 vs. Chapter 13 and What Qualifies
Chapter 7 is sometimes called liquidation bankruptcy. A trustee may sell property that is not exempt and pay the proceeds to creditors, but because Illinois exemptions protect many common assets, most individual cases involve no sale at all. The case usually ends with a discharge within a few months, and you make no repayment plan payments. That speed is one reason Chapter 7 bankruptcy is often the fastest path to relief for people with little income left over after basic expenses.
Chapter 13 bankruptcy works differently. You keep all of your property and repay part of your debt through a three- to five-year plan. People usually choose Chapter 13 when they are behind on a mortgage and want to keep the home, or when they earn too much to qualify for Chapter 7.
Eligibility for Chapter 7 depends mainly on income. If your household income is below the Illinois median for your household size, you generally qualify. If it is above, the means test compares your income with allowed living expenses to decide whether you can afford to repay some of your debt. Certain debts, including child support, most student loans, and recent taxes, generally survive a Chapter 7 discharge.
If a trustee would likely sell something you cannot afford to lose, we will tell you before you file, and filing under Chapter 13 instead could protect it.
What Should You Bring to Your Chapter 7 Bankruptcy Consultation?
Bring what you can gather. These records help us check your eligibility and review your property against Illinois exemptions during the meeting.
- Pay stubs or other proof of income for every household member who works
- Recent bills and statements from credit card companies, medical providers, and lenders
- Titles or loan statements for any vehicles, and your mortgage statement if you own a home
- Bank and retirement account statements
- Any lawsuit papers, judgments, or garnishment notices
A first consultation costs nothing. You will learn whether you qualify for Chapter 7, which of your property is protected, and what filing would involve.
What Is The Chapter 7 Bankruptcy Case Timeline?
Most Chapter 7 cases move from filing to discharge in a few months.
- Credit counseling. You complete a short online or phone course with an approved agency before the case is filed.
- Filing. We file your petition, schedules, and means test forms. The automatic stay, an order that requires most creditors to stop collecting from you, begins immediately.
- Document review. Before the meeting with the trustee, we send the trustee your tax returns, recent pay records, and identification.
- Meeting of creditors. A few weeks after filing, the trustee asks you questions under oath. The trustee's meeting is usually brief.
- Financial management course and discharge. You complete a second short course. If no one objects, the court enters your discharge, typically within a few months after the meeting.
What Are Important Aspects of a Chapter 7 Bankruptcy Case?
Recent financial activity receives close attention. Trustees review payments to relatives, transfers of property, and large charges made shortly before filing. Paying back a family member before you file, for example, can allow the trustee to recover that money from the relative. As Chapter 7 lawyers in Bolingbrook, we review these transactions with you before choosing a filing date.
Cars and other financed property need a decision. You can keep a car by staying current and signing a reaffirmation agreement, which is a new promise to repay that loan, or you can return the car and discharge the remaining balance. If a lender is already threatening to repossess your car, filing promptly stops the repossession while you decide.
Every asset and debt must be disclosed, including property you think has no value. Errors when filing without a lawyer are a common reason cases are delayed or discharges are denied.
A Chapter 7 filing remains part of your credit history for a long time. Even so, rebuilding credit after discharge usually begins within months of the discharge as you make on-time payments on new or remaining accounts.
Northern District of Illinois Bankruptcy Court and Local Resources
Chapter 7 cases from Bolingbrook, in both Will County and DuPage County, are filed in the U.S. Bankruptcy Court for the Northern District of Illinois, Eastern Division. A panel of private Chapter 7 trustees handles the cases.
- NDIL Chapter 7 information. The court posts its required-documents checklist for Chapter 7 filers here, along with an interactive Chapter 7 timeline.
- Trustee document preferences. Each Chapter 7 trustee in the Eastern Division sets deadlines and methods for receiving tax returns, pay records, and ID before the meeting of creditors. This chart lists them.
- Credit reporting information. The court explains that it does not report to credit bureaus and how to dispute inaccurate entries after your case.
- Means testing data. The U.S. Trustee Program publishes the median income figures and expense standards used in the Chapter 7 means test.
Reach Out to Madden Law LLC to Schedule a Consultation
Chapter 7 can clear most credit card and medical debt in a matter of months. A free consultation with Madden Law LLC will confirm whether you qualify and show you what you would keep. Appointments are available on weekday evenings and Saturdays. Contact us to speak with a Chapter 7 bankruptcy attorney serving Bolingbrook, IL.